Fall 2026 Home Buyer Guide: Greater Boston Real Estate

Mike Hughes Team | Fall 2026
Fall 2026 Buyer's Guide:
Navigating the Greater Boston Market
Everything you need to know to buy a home this fall, from understanding today's market to making your strongest offer.
Why People Buy
Top 10 Reasons Buyers Purchase a Home
Whether you are buying for the first time or making your next move, the motivations that drive homeownership are remarkably consistent. Here are the ten reasons buyers most commonly cite, backed by research from the National Association of REALTORS and other leading sources.
-
The desire to own a home of your own. Consistently the most cited reason buyers purchase. In NAR's 2024 survey, 64% of first-time buyers named this as their primary motivation. Owning your own home is a deeply personal milestone that no rental can replicate.
Source: NAR Profile of Home Buyers and Sellers, 2024 -
A home is a proven financial investment. 79% of buyers believe purchasing a home is a good financial investment, and 39% of those say it outperforms owning stocks. Long-term appreciation, equity growth, and leverage make real estate one of the most accessible wealth-building tools available.
Source: NAR Profile of Home Buyers and Sellers, 2024 -
Control over your living space. 94% of homeowners cite control over what they do with their home as a key benefit. Paint the walls, renovate the kitchen, plant a garden, get a dog. You set the terms.
Source: NAR Promoting Home Ownership consumer survey, nar.realtor -
Privacy and security. 91% of homeowners cite a sense of privacy and security as a meaningful benefit. A home that is yours provides stability and peace of mind that month-to-month tenancy simply cannot.
Source: NAR Promoting Home Ownership consumer survey, nar.realtor - Putting down roots in one place. Moving is disruptive and expensive. Owning lets you decide how long you stay, rather than having that decided for you at each lease renewal. The longer you stay, the further the one-time costs of buying and selling are spread out.
-
Building long-term equity. Buyers who purchased 10 years ago have gained an average of $225,000 in equity. Each mortgage payment reduces your loan balance and builds an asset you own outright over time. Rent payments build wealth for your landlord.
Source: NAR Promoting Home Ownership, nar.realtor -
Predictable, stable housing costs. A fixed-rate mortgage locks in your principal and interest payment for the life of the loan. Rent has no ceiling. U.S. shelter costs have risen significantly decade over decade, while your locked-in mortgage payment stays the same.
Source: U.S. Bureau of Labor Statistics, Consumer Price Index (Shelter component) -
Community belonging and civic roots. Homeowners are more likely to vote, volunteer, and invest in their neighborhoods than renters, regardless of income level. Stable housing creates a deeper connection to the community around you.
Source: NAR Social Benefits of Homeownership and Stable Housing, 2012 -
Tax advantages of homeownership. Homeowners may deduct mortgage interest and property taxes from taxable income. Upon sale, an individual filer can exclude up to $250,000 in capital gains from federal taxation, and up to $500,000 on a jointly filed return.
Source: IRS Publication 936; IRS Section 121 -
Creating long-term, transferable wealth. A home is an asset that can be passed on, anchoring financial security beyond your own lifetime. The wealth gap between owners and renters compounds significantly over time.
Source: Federal Reserve Survey of Consumer Finances; Harvard Joint Center for Housing Studies
Fall 2026 Market Check
What's Happening in the Housing Market Today?
If you've been on the sidelines waiting for the "right time" to buy, here is your honest read on where things stand this fall. Three questions buyers ask me most often:
What's going on with mortgage rates?
They have gone up, and that is the plain truth of this fall. The 30-year fixed averaged 7.40% in Freddie Mac's Primary Mortgage Market Survey for the week of October 8, 2026, up from 7.28% the week before and from 6.30% a year earlier. The 15-year fixed averaged 6.73%. Nobody can tell you where rates go next. What you can control is whether you are ready to act when a house you want comes along, and what you borrow against it.
Are home prices still going up?
Yes, and in this region faster than nationally. The FHFA House Price Index rose 2.6% nationally from July 2025 to July 2026, and 4.1% across the New England census division over the same twelve months. For Massachusetts specifically, FHFA puts single-family appreciation at 3.64% for the year ended 2026Q2. Locally, the average Massachusetts single-family sale price is $876,220 year to date, up 2.08% from $858,377 over the same stretch of 2025, on figures as of October 9, 2026. Prices are not falling.
Is more inventory coming to market?
Substantially, yes, and this is the real story of fall 2026 for buyers. Massachusetts single-family listing inventory stood at 8,667 units on October 9, 2026, against 6,774 on the same date in 2025: an increase of 27.95%. Months of supply moved from 2.09 to 2.68 over the same year. Nationally, NAR reported 4.9 months of supply for August 2026, its highest in over ten years, with 1.62 million homes on the market. More supply at every level is more choice for you.
Bottom line: borrowing costs are higher than a year ago, prices are still climbing, and inventory has grown by more than a quarter. That combination means less competition per house and more room to negotiate than buyers have had in several years. The trade-off is real, and which side of it matters more depends on your own timeline rather than on a headline.
The Core Trade-off
The Difference Between Renting and Buying a Home
A lot of buyers ask whether renting is the safer choice right now. Here's what the data says:
Rents Keep Rising
The national median rent has increased substantially over the past decade. There is no cap on what a landlord can charge at renewal. A fixed-rate mortgage locks in your payment today.
A Home Is a Tangible Asset
Every mortgage payment builds equity you own. Rent payments build equity for someone else. After 30 years, a homeowner has a paid-off asset. A renter has receipts.
Wealth Grows Over Time
Homeowners consistently accumulate significantly more net worth than renters over a 10-, 20-, and 30-year horizon, driven by equity growth and price appreciation.
"If you're in a financial position to do so and ready to stay put for at least a few years, buying a house is totally worth it."
Bankrate
Your Buying Power
What Today's Mortgage Rates Mean for Your Monthly Payment
With the 30-year fixed averaging 7.40% in the week of October 8, 2026, here is what different loan amounts look like in monthly principal and interest. These are P&I only, before taxes and insurance, across the range most relevant to Greater Boston buyers:
| Loan Amount | At 8.5% | At 8.0% | At 7.40% (Today) | At 7.0% | At 6.5% |
|---|---|---|---|---|---|
| $500,000 | $3,845 | $3,669 | $3,462 | $3,327 | $3,160 |
| $750,000 | $5,767 | $5,503 | $5,193 | $4,990 | $4,741 |
| $1,000,000 | $7,689 | $7,338 | $6,924 | $6,653 | $6,321 |
| $1,250,000 | $9,611 | $9,172 | $8,655 | $8,316 | $7,901 |
| $1,500,000 | $11,534 | $11,006 | $10,386 | $9,980 | $9,481 |
Figures are estimated principal and interest only. Taxes, insurance, and HOA fees are additional. Consult your lender for a personalized payment estimate.
Two things are worth drawing out of that table. First, half a point of rate is real money: on a $750,000 loan it is roughly $250 a month, about $3,000 a year. Second, and less obvious, rate relief tends to arrive with company. When borrowing gets cheaper, more buyers can qualify and they compete for the same houses, which pushes prices up. A lower rate on a higher price is not automatically a better deal. The more useful question is not "where will rates be" but "what payment am I comfortable with", and then what that payment buys you today.
Live Market Data
Greater Boston County Market Review
Single-family homes only · Three months ending October 9, 2026 · Updated monthly · Source: MLS PIN Area Market Survey
Source: MLS PIN Area Market Survey (AMS), single-family homes, three months ending October 9, 2026 (Start Date 7/9/2026, End Date 10/9/2026). Months of Supply = Active Listings ÷ (Closings ÷ 3 months), a figure we derive from the two counts above rather than one the report prints. Sale-price-to-list-price ratio over the period: Middlesex 102%, Norfolk 101%, Suffolk 100%, Essex 102%.
Fall 2026 Opportunity
Why This Fall Is a Good Time to Buy
Let me be straight with you: this is not a rates argument. At 7.40% nobody is going to tell you borrowing is cheap. The case for buying this fall rests on three other things, and they are the ones that actually decide how a purchase goes.
You have more to choose from than you have had in years
Massachusetts single-family inventory is up 27.95% year over year, 8,667 listings on October 9, 2026 against 6,774 a year earlier. Nationally NAR counted 1.62 million homes for sale in August 2026 and 4.9 months of supply, the highest in more than a decade. More inventory is the single biggest change in this market, and it lands squarely in your favor.
Fall buyers compete against fewer people
Spring and summer bring the crowds. By October the casual lookers have dropped away and what remains on both sides of the table is people who actually need to move. Across the four counties we track, homes that sold over the three months ending October 9, 2026 went for between 100% and 102% of list price. That is a market where a well-reasoned offer gets a real hearing, not one where you are bidding against eleven strangers.
Waiting has a price too, and it is not zero
The Fannie Mae Home Price Expectations Survey for Q3 2026 puts the panel's mean forecast at 2.5% national price growth for 2026 and 2.2% for 2027. Massachusetts has been running ahead of the national number: FHFA has state single-family prices up 3.64% for the year ended 2026Q2. If you wait a year for a rate that may or may not arrive, you are likely bidding on a more expensive house when you get there. That is the trade nobody puts in a headline.
None of this means you should buy if you are not ready. It means the thing that usually stops buyers, no choice and too much competition, is the thing that has eased most this fall.
Long-Term Value
How Homeownership Builds Wealth Over Time
One of the most important reasons to buy is what happens to your net worth over time. The data is not subtle:
"A monthly mortgage payment is often considered a forced savings account that helps homeowners build a net worth about 40 times higher than that of a renter."
Lawrence Yun | Chief Economist, National Association of REALTORS
Homeownership forces a discipline that renters rarely replicate through voluntary savings. Each payment reduces your principal balance and builds equity that belongs to you, not your landlord.
The current figures: ATTOM's U.S. Home Equity and Underwater Report for Q2 2026 puts 41.1% of mortgaged residential properties in the "equity-rich" category, meaning a loan-to-value ratio of 50% or lower. That share has been falling, from 43.3% in Q1 2026 and 47.4% in Q2 2025, which is what you would expect as more recent buyers with smaller deposits enter the pool. Average equity per mortgaged owner was $310,000 nationally in Q2 2026, and $486,000 in Massachusetts, the third highest of any state (Cotality, formerly CoreLogic, Homeowner Equity Insights, published September 10, 2026).
The long view is the one that matters most here. FHFA's house price index for the Boston metropolitan division is up 418.05% since the first quarter of 1991, against 335.69% nationally and 337.20% across New England, on figures for the period ended 2026Q2. Over that span this region has outpaced both the country and its own census division. No single year of that was comfortable to live through while it happened.
Inventory Update
Are More Homeowners Selling?
Yes, and it's meaningful. Here's what the data shows:
Massachusetts owners brought 43,168 single-family listings to market year to date in 2026, against 41,933 over the same stretch of 2025, an increase of 2.95%. The more striking number is what is sitting unsold: inventory on October 9, 2026 was 8,667 units versus 6,774 a year earlier, up 27.95%. Listings are arriving at a similar pace and clearing more slowly, which is how supply builds. Closed sales were down 0.80% year to date, at 29,314 against 29,550.
What that means for you in Greater Boston: you have materially more homes to choose from than a year ago, and the ones you look at have usually been available longer. That is not a soft market. Statewide days on market for sold homes went from 38 to 41, which is three days, not a collapse. It does mean you are less likely to lose five listings in a row before landing one.
For buyers who have spent two years feeling squeezed by a lack of options, this is the most selection there has been in several years, and fall is when it peaks before the winter slowdown.
Your First Move
Why Pre-Approval Is Even More Important This Fall
Getting pre-approved before you tour a single home is not optional in today's market. Here's why it matters more than ever:
What pre-approval actually means
A pre-approval letter is a written commitment from a lender saying they've reviewed your financial documentation (income, assets, credit) and will lend you up to a specified amount, subject to appraisal and final underwriting. It's not the same as a pre-qualification, which is just an estimate based on what you told the lender.
Why sellers require it
Because it is the first thing the other side checks. Over the three months ending October 9, 2026, homes that sold in Middlesex County went under agreement in an average of 22 days and closed at 102% of list price. Norfolk and Essex averaged 23 days, Suffolk 27. That is not a market that waits while you arrange financing. When an offer arrives without a pre-approval letter attached, a listing agent reads it as the weaker of two otherwise similar offers, and that is usually the end of it.
If you take one thing from this guide, take this: get pre-approved before you tour anything. It is free, it takes a few days, and it is the difference between being a buyer and being a browser.
What it takes to get pre-approved
Your lender will typically need:
- W-2s or 1099s from the past two years
- Recent pay stubs (30 days)
- Bank and investment account statements (2-3 months)
- Photo ID
- Consent to pull your credit
Most lenders can turn around a pre-approval in 1-3 business days. Don't wait until you find the right house. Get it done this week.
After You Apply
Things to Avoid After Applying for a Mortgage
Once your mortgage application is in, your financial picture needs to stay exactly as the lender saw it until closing day. Common mistakes that can delay or kill your closing:
- Do not apply for new credit. A new car loan, credit card, or any inquiry can lower your credit score and change your debt-to-income ratio. Both affect your approval.
- Do not make large cash deposits without documentation. Lenders will ask about any unusual deposits. "I was holding it for a friend" is not a sufficient answer.
- Do not quit or change your job. Lenders verify employment right before closing. A job change, even a promotion to a new employer, can require a new application cycle.
- Do not co-sign a loan for anyone. It doesn't matter that you don't expect to pay it. It still shows as your debt.
- Do not make large purchases on credit. New furniture, appliances, or a car on credit before closing has torpedoed more deals than buyers realize.
The rule is simple: no major financial moves between application and closing without checking with your lender first.
On the Tour
What to Watch For When You Tour a Home
A red flag is not a defect. It is a visible sign that a defect may be there. You are not inspecting the house on a tour and you should not try to: you are deciding which questions are worth paying a professional to answer. Three principles make the difference between looking and seeing:
- Several red flags in one place matter far more than one on its own. A single hairline crack is usually nothing. A crack, plus a door that will not latch, plus a sloping floor in the same corner of the house, is a pattern. Patterns are what you tell your inspector about.
- Age changes what a flag means. Minor settling in a hundred-year-old house is expected. The same sign in a home built eight years ago is a much bigger question. By the same logic, an older home with almost no red flags is genuinely impressive and worth noticing out loud.
- Water is the common thread. Most of what goes expensively wrong in a house traces back to water that went somewhere it should not have. If you only have the attention for one category, make it this one.
Outside
Walk the full perimeter before you go in. Does the ground slope away from the foundation, or toward it? Where do the downspouts discharge, and is it far enough from the wall to matter? Look at the hard surfaces: cracks in the driveway, walkway and patio tell you about movement in the ground underneath. Check the roof plane for sag or patching, the flashing where roof meets wall or chimney, and the gutters for the rust streaks that mean they overflow. Note retaining walls that lean, trees close enough to reach the roof or the sewer line, and decks, railings and stairs that move when you lean on them. On a sloped lot, pay particular attention to the uphill side.
Inside
Start in the basement or crawl space, because that is where the house tells the truth about itself. Look for staining on the walls, a visible water line, efflorescence (the chalky white deposit left behind when water passes through masonry), rust at the base of appliances and posts, and flooring that has cupped or lifted. A dehumidifier running in October is information. Above that: cracks that run diagonally from the corners of door and window openings, doors and windows that stick or will not close square, floors that are visibly out of level, sagging beams or joists, and a fireplace or chimney that is pulling away from the wall. Open every closet and look up: fresh paint confined to one ceiling is a story. Run the water in every fixture at once and watch the pressure. Note the age of the furnace or boiler, the water heater and the electrical panel, all of which are usually printed right on the unit.
The one area to hand straight to a specialist
Environmental questions, which in older Massachusetts housing stock means lead in paint and pipes, asbestos in insulation and flooring, radon, underground storage tanks and buried oil tanks, are not something to assess on a tour and not something we advise on. The rules and the testing have changed substantially over the years. If you see or suspect any of it, that is a licensed specialist's work, and the time to engage one is during your inspection window, not after.
Trust Your Nose
What's That Smell? Six Odors Worth Noticing on a Tour
Your nose is the one inspection tool you already own, and it works before you have hired anybody. Most homes smell like something, and a candle or fresh paint is not a red flag on its own. What matters is an odor that stays in the same part of the house, because a smell that holds its position is usually attached to something physical. Note it, note where you were standing, and let a licensed inspector or the right specialist tell you what it is. One odor in one spot is a question. The same odor in the same spot on a second visit is a question worth paying to answer.
- Rotten eggs or sulfur. Gas is odorized on purpose so that a leak can be detected by smell. Pay attention near the furnace, water heater, range and dryer, and in spaces with little ventilation such as a utility closet or a crawl space. Do not keep sniffing to be sure and do not touch switches. Step outside and call the gas utility from there. After that, have the appliances and lines checked by a licensed technician before you go any further.
- Damp, musty, basement air. This is moisture that has been somewhere long enough to leave a signature. Basements, crawl spaces, attics, under sinks, around tubs and showers, behind and beneath laundry and dishwashers. Sustained moisture damages framing and finishes, and it is the condition mold needs. This odor also tends to survive a house that has been aired out for a showing, so trust your nose over a fresh coat of paint. Look for the matching evidence: staining, chalky residue on foundation walls, a dehumidifier running, flooring that has cupped. Then put moisture at the top of your inspection list.
- Sweet and faintly syrupy. Refrigerant. Check around the air handler or AC unit, a heat pump, the back of the refrigerator, and under sinks near cabinets. A coolant leak means a system losing capacity and a repair that may arrive sooner than you budgeted for. Ask the age and service history of the heating and cooling equipment, and have it evaluated rather than estimated.
- Sharp ammonia. Three very different causes share this one smell: a refrigerator coolant line or defrost pan, a washing machine hose going brittle, or an animal that got into a cavity and did not get out. Look in the kitchen near the refrigerator or freezer, at laundry floor drains, in bathrooms and in crawl spaces. The first two are appliance and water problems. The third is a sanitation problem, and it also tells you something can get inside the structure. Ask when the washer hoses were last replaced, and have the inspector look for entry points.
- Fishy, or like hot plastic. The most commonly missed odor on this list and the worst one to walk past: overheating wiring, a failing outlet, or a switch or breaker working harder than it should. Check at switches and outlets, especially any that feel warm, at the panel, and anywhere a large appliance is plugged in. This is a fire-risk signal, not a nuisance. Stop using the outlet, write down its exact location, and have a licensed electrician evaluate it before you close.
- Sewage, or sour drains. Cracked or leaking waste lines, a trap that has dried out, a blocked vent, or a drain that needs clearing. Bathrooms near toilets and shower drains, kitchen drains, basement and laundry floor drains. It can be a small clog or a sewer line, and the smell alone will not tell you which. Run water in every fixture while you are touring, and ask when the sewer line was last inspected.
Keep a note on your phone as you go: the odor, the room, the time of day. Hand that list to your inspector. Questions about anything you noticed on a tour: 617-433-9225.
When You're Ready to Buy
Advice for Making Your Strongest Offer on a Home
When the right home comes along, you want your offer to be the one that gets accepted. Here's what separates winning offers from the rest:
- Lean on your agent's knowledge of local market conditions. In Greater Boston, some towns have very different pace and multiple-offer dynamics than others. The strategy that worked in one town may hurt you in the next. Your agent's job is to know this and advise accordingly.
- Have your pre-approval letter ready to attach. Sending an offer without a pre-approval letter signals that you are not ready. Every serious offer comes with financing documentation.
- Make a fair offer based on comparable sales, not wishful thinking. Lowball offers in a seller's market are typically not entertained. They can also put the listing agent and seller in a defensive posture that makes a deal harder to get done even if you come back at full price. Come in informed.
- Trust the negotiation process. A counter-offer is not a rejection. Most deals involve at least one round of negotiation. The goal is getting to a number that works for both sides, not winning an argument. Your agent's job is to keep the deal moving toward the table.
Your Best Decision
Why You Should Work with a Real Estate Agent When You Buy
In the age of Zillow and Redfin, buyers sometimes wonder if they need an agent at all. The data and the reality of the transaction consistently say yes. Here's why:
Industry Experience
Agents know what's behind the listing: inspection history, seller timeline, why the price changed, what the neighborhood is actually like. You can't get that from a website.
Expert Market Insights
What is this home worth compared to recent closed sales? Is the list price fair? Is the market moving fast or slow right now? These questions require a live professional with local data, not an algorithm.
Pricing Strategy
An experienced agent knows whether this home is correctly priced, overpriced, or actually underpriced relative to recent comps. That knowledge shapes your offer strategy.
Contract Expertise
A purchase and sale agreement has deadlines, contingencies, and clauses that protect you. One missed deadline or misunderstood contingency can cost you thousands or your deposit.
Marketing Access
Buyer's agents often know about coming-soon listings, pocket listings, and off-market opportunities before they hit public sites. In a low-inventory market, that network is real value.
Skilled Negotiation
Negotiating directly against a listing agent who does this full time is not a fair fight. Having your own advocate at the table is how buyers avoid overpaying and protect their interests through closing.
In Massachusetts, buyer agent compensation is negotiable and is agreed in writing with you before you start touring, so you will know exactly what representation costs and who pays it before you commit to anything. Ask me and I will walk you through it in plain terms. There is no reason to navigate one of the largest financial decisions of your life without a professional in your corner.
Ready to Talk About Buying This Fall?
Whether you have questions about the market, want to know what you can afford, or you're ready to start touring homes, I'm here. A conversation costs nothing.
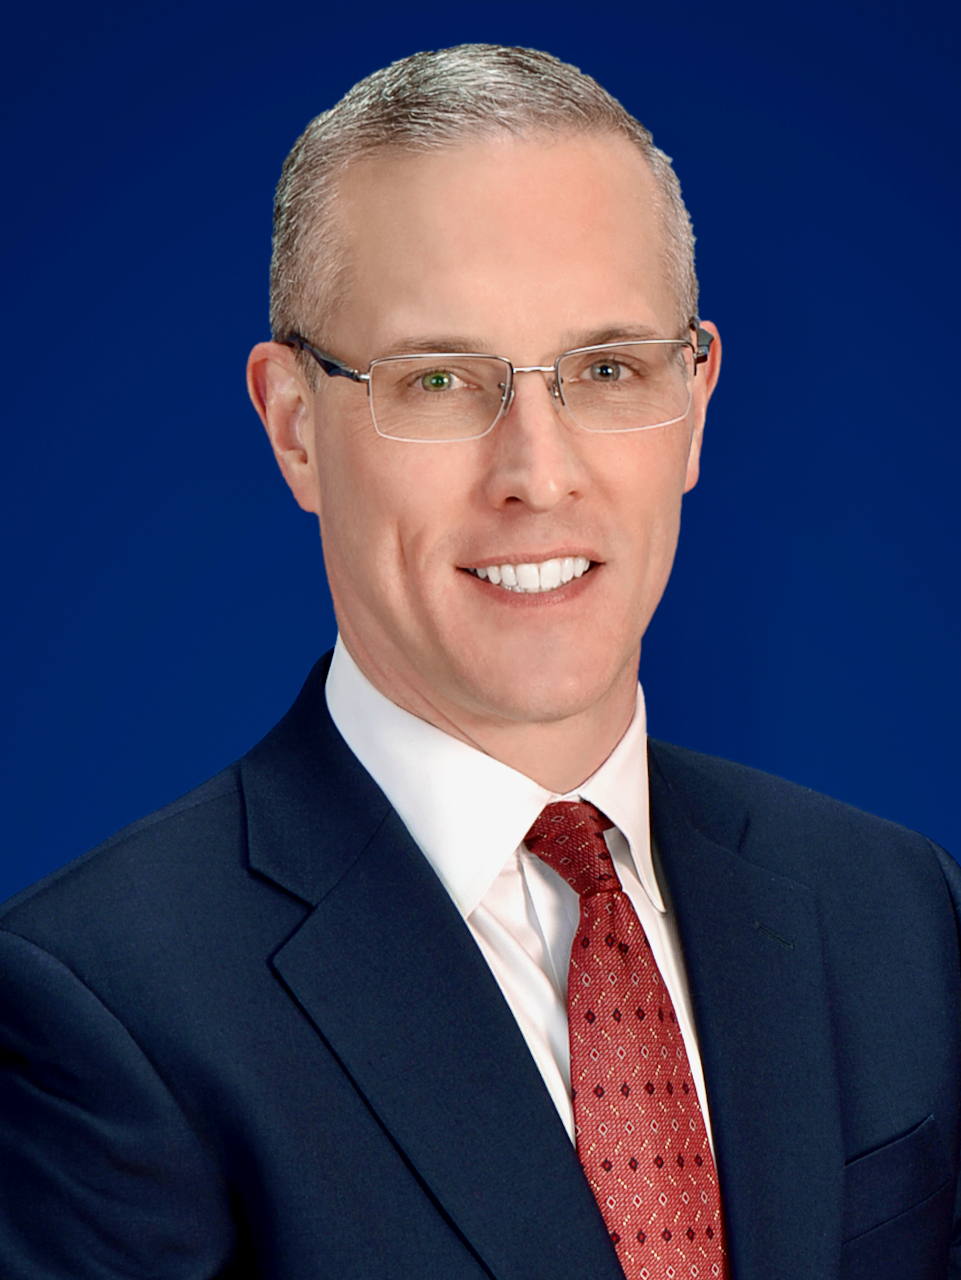
Mike Hughes
Broker Associate | Mike Hughes Team | eXp Realty
Free Resource
Get the Home Buyer Red Flag Checklist
Before you make an offer, know what you’re looking at. This free checklist walks you through the most common red flags home buyers miss, so you can negotiate from strength or walk away before it’s too late.
Get the Free ChecklistStay in the Loop
Get the Greater Boston Market Update Every Month
Mike’s monthly newsletter covers market stats, community spotlights, and what’s actually happening in Greater Boston real estate, delivered free to your inbox.
Subscribe: It’s Free

